Investor Relations Content That Earns a Second Meeting
November 18, 2026
“When the apartments are ready, let me know what they rent for.” A prospective limited partner (LP) leaves your meeting with that request. Three months later, your newsletter announces that renovations finished on schedule. You’ve given the investor good news and left their question unanswered.
Useful investor relations content starts with the question someone will remember asking. Between raises, that means giving existing LPs a dependable account of what changed in their investment and giving prospective LPs a reason to pick up an earlier discussion. Sometimes the difference between another email and a second meeting comes down to which rent figure you put in the first sentence.
The rent figure your follow-up should lead with
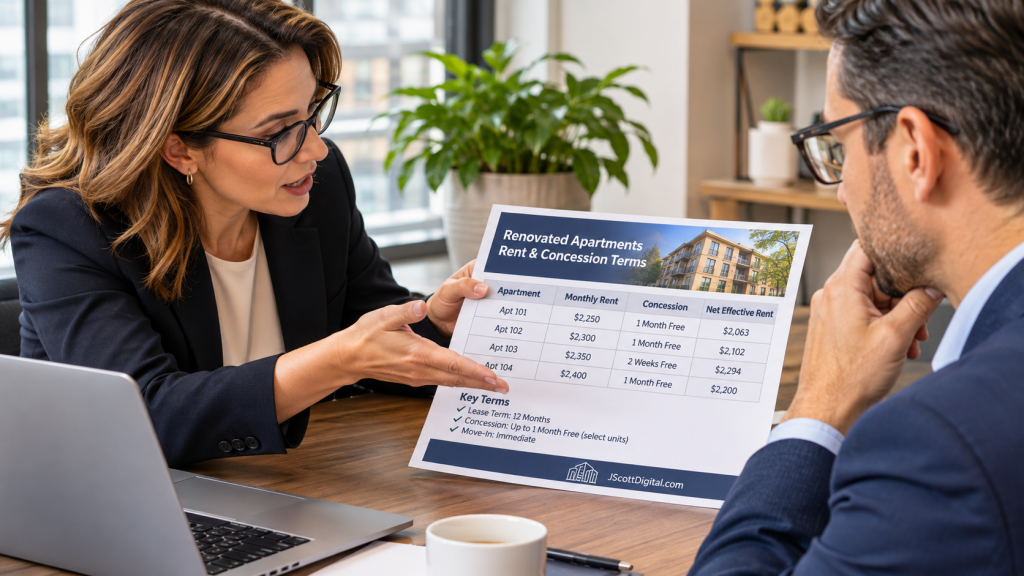
Imagine you budgeted $1,600 per month for each renovated apartment, with no free rent. The first four residents sign twelve-month leases at $1,650 a month. Your leasing manager gives each resident the first month free. What do you tell the investor who asked about rents?
“We averaged $1,512.50 a month after concessions on the first four leases, $87.50 below budget.” That sentence gives your reader the result, the comparison, and the size of the sample. The arithmetic is simple enough to include in a parenthesis if needed. Eleven paying months at $1,650 generate $18,150 in contracted rent per apartment, which you spread over the twelve-month term. Keep the word “contracted” if collections haven’t started.
The next sentence should explain a decision. Suppose several qualified renters toured the property twice and hesitated over the cost of moving. Your leasing manager offered the free month to fill the first units and now wants to try a smaller concession. That detail tells the LP why you accepted less rent and which assumption the next leases will test. A photograph of a finished kitchen can sit farther down the page.
What changes for someone who already owns an interest in the fund
An existing LP may read the same rent figure and wonder whether to revise a cash forecast. Four leases alone won’t answer that question. Find out how many apartments the budget assumed would generate rent this quarter, when residents actually moved in, and when they owe their first payments. A free month at the start of a lease has a different near-term cash effect from the same concession in month twelve.
Ask fund accounting to carry those dates through the property forecast and check the fund’s share. If the expected distribution holds, say which forecast you reviewed and when. Where an open issue could change the answer, identify it. “We’ll revisit the June distribution once we have May collections” gives your LP more to work with than a paragraph about healthy leasing traffic.
A reporting calendar your LPs can plan around
Start with the dates your fund has committed to in its agreements and investor communications. Give each recurring item a clear description on the investor calendar. A quarterly portfolio update tells LPs how the investments performed. A capital account statement answers questions about an individual investor’s interest. If the two arrive on different dates, show both dates and say where each document will appear.
Fund accounting can tell you when the books will close. Asset management can tell you how soon after close it can explain a variance. Work backward from delivery with both teams and leave time for them to reconcile their figures. The NCREIF PREA reporting standards provide a reference for institutional real estate reporting, including fund performance and investor-specific reporting. Use your fund’s commitments to set its delivery dates.
Give prospects a different schedule. At the end of a meeting, record the question, the evidence you’ll need, and when someone on your team will have it. For the apartment example, four signed leases might justify an initial note. A comparison of two concession offers has to wait until renters have had a chance to respond to both. If leasing takes longer than you expected, send a brief status update on the date you promised.
When a portfolio update should go out early
Suppose a contractor pushes the next apartment release back two weeks. Before emailing every LP, ask what the delay changes for them. If your team can absorb it within the existing budget and schedule, explain it in the regular update. If it changes cash you’ve told investors to expect, bring the revised forecast to the people responsible for investor communications and any formal notices.
You can send a useful interim update while a figure remains open. Identify the affected properties or units, state what you know about timing, and give a date for the next answer. For example, “The contractor moved completion of the final six apartments from May 1 to May 15. We’re reviewing the effect on June cash receipts and will update you on May 20.” Assign that May follow-up to a person with access to the forecast.
Which market facts explain the rent decision?
Before drafting a market paragraph, ask your leasing manager which other buildings prospects mentioned on tour. Check asking rents and concessions for comparable floor plans at those properties over the same dates. A competitor advertising six weeks free on a two-bedroom apartment may reserve that offer for an eighteen-month lease. Include the term before you compare it with your own offer.
Regional evidence serves a different purpose. The Federal Reserve’s Beige Book draws primarily on qualitative information that the regional Reserve Banks gather from contacts across their districts. If contacts report wider use of concessions, that observation gives you a question to ask locally. The offers your renters could actually get down the street help explain the decision you made at the property.
Keep the commentary proportionate to what you found. Two competing properties offering a free month can justify a closer look at your pricing. They give you little basis for a claim about apartment demand across the metro area. Where local evidence conflicts with the regional account, say what differs. An LP can understand why a newly renovated building competes aggressively for its first residents even while established properties nearby hold rents steady.
Four questions to ask of your last investor email
Open the replies to a recent portfolio update. Choose one that took several exchanges to resolve and trace it back to the line that prompted it. Use these questions during your next editorial review.
Could the reader identify the comparison? “Ahead of plan” means little if you budgeted for signed leases and reported apartment tours. Put the actual and budgeted figures on the same basis.
Did the update identify who felt the impact? A property can miss its rent target while the fund remains on track for a distribution. Explain the link if you’ve verified it, or tell the reader when you’ll know.
Did the reader know when to expect an answer? If several LPs asked when statements would arrive, give the delivery date in the email they receive before the statements appear.
Which reply deserves time with the investment team? Send a missing figure by email. Save meeting time for a question that calls for judgment, such as how long you’d accept vacancy to protect rents.
If the same questions keep coming back each quarter, use the prompts below to find out why. You can also work with J. Scott Digital to revise the portfolio updates and investor emails behind those replies.
The invitation after the next four leases
When the second group of residents signs, return to the investor’s original request. Calculate rent on the same basis for both groups and check how long each group of apartments stood ready before residents moved in. A smaller concession can improve the lease rate while a longer vacancy consumes the gain. That’s a decision an allocator may want to discuss with the person who made it.
For example, suppose you cut the concession by $825 per apartment and keep the same monthly rent. At $1,650 a month, an empty apartment costs roughly $55 a day in forgone rent on a thirty-day basis. Fifteen extra vacant days would use up the $825 you gained. If the second group took ten extra days to move in, your rough gain would be $275 per apartment before other costs. An investor can use that comparison to ask a much better question about the next release. How many extra days would your team risk to hold the higher rent?
Your invitation can be brief. “When we met in March, you asked what renters would pay after renovation. We now have eight signed leases and can compare the rent we gained by reducing the concession with the extra days the second group stood empty. Would you like to walk through those figures with our asset manager?”
Share the figures your firm has cleared for that audience. By the time the allocator accepts, they know what you’ll discuss, who can answer their questions, and why it was worth waiting for eight leases.